Sunday, June 25, 2006

A Cheapskate's Guide to Home Security

We just got a security system installed. The whole experience prompted me to blog on some cheapskate home security ideas.

The whole point of cheapskate home security is based on deterrence. Here's my ideas:

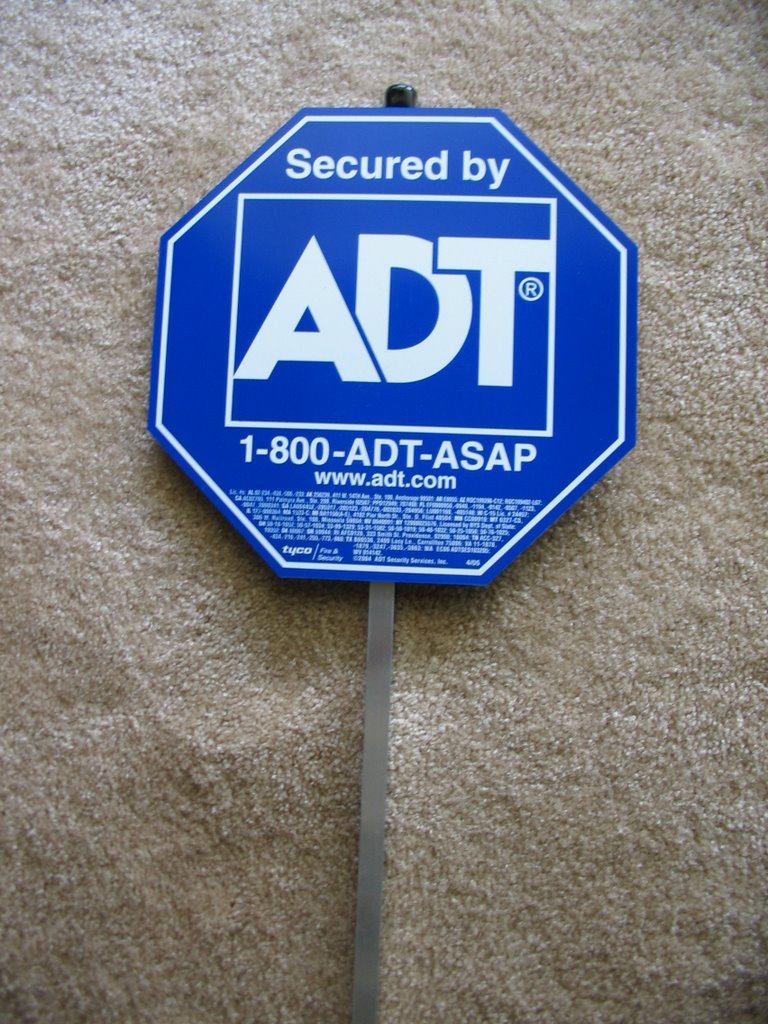
(1) Find a friend who pays for security service and get one of their signs. Security companies usually give two or three with an installation. Perhaps, your friend has a spare. Once you get the sign, put it up in your front yard.

(2) When on travel, use some timers for your indoor lighting. Here's an Amazon search of indoor light timers.

(3) Consider using random security measures for your house so that someone planning an burglary doesn't get a good read on your routine. Here's some ideas:

(a) Cycle between your outdoor lighting scheme. Rather than have all of your outdoor lights on, cycle between using your lights for your front door, back door and/or garage
(b) If you have a garage, don't always use it.
(c) You can probably come up with a few others.

(4) If you're traveling, stop your mail or have a friend pick it up.

(5) Consider a baseball bat or other weapon near your bed. This may be suitable if you're not scared of conflict and you don't have a sophisticated alarm system (with sensors for windows, glass break sensors, etc).

(6) Plant thorny bushes near potential access points.

(7) Set up motion sensors on your exterior lighting.

(8) Get a dog. A cheapskate alternative is if your neighbor has a dog that shares your fence line. We've got this situation and their dogs always bark when I walk in my back yard.

(9) Consider getting signs such as "This house protected by Smith and Wesson" and/or "Beware of dog." Even if you don't have a dog or a handgun, it could be a deterrent.

(10) Keep your grass cut, don't let your newspapers pile up.

(11) Get dead-bolt locks.

Adopting all of these ideas is certainly not cheap. However, a homeowner or renter could probably take a few of these ideas and come up with a low cost alternative. Additionally, if you're a real cheapskate, remind yourself of the true expense of having a home intrusion/burglary occur (might be a little incentive to open the wallet/purse).

Wednesday, June 21, 2006

Finance Junkie Setting Up Lending Group at Prosper.com

I've taken the first steps towards setting up a lending/borrowing group at Prosper.com. The group's name is tentatively "Feng Shui Financing."

Right now, membership is set at invitation only. Email me if you desire to be associated with this group. I tentatively plan on:

(1) Finishing the group's prosper profile within the next three weeks.

I will reconsider relaxing the group's restrictive invitation only membership policy closer to the time that the group's profile page is finished. These next three weeks will allow me time to pattern Feng Shui Financing after the best bits and pieces of other prosper groups.

Please leave recommendations as necessary in my comments section.

Don't Have a Prosper Lending Account? Haven't Funded Your Account Yet? Don't Bother!

You can read my latest posting on prosper lending here... You can always come back to the below posting.

The title is a little bit misleading. It's actually my opinion that you should DELAY funding your account. Here's the reason why:

(1) Lenders and their deep pockets appear to be growing at a faster pace than borrowers willing to submit good applications. I define good as prosper borrowers appropriately setting the interest rate they're willing to pay in line with their credit grade. I'm finding TOO many cases of people with the worst two possible credit grades asking for loans at rates around 10%. Get real! Prosper.com's primary mission is not to provide a forum for charity. (Enough of my rant)

(2) This imbalance between lenders and borrowers is causing some of the good loans to get bid down to lender risk adjusted rates equivalent to a Certificate of Deposit.
- Prime example: Within the last 48hrs I watched a "D" credit graded teacher get a roughly 12.9% interest rate on her loan. Working backwards (by trial and error), prosper.com's auto fill calculator shows me that lender's bidding on this loan got a risk adjusted return of only 6.7%. On top of this, they're assessed Prosper's 0.5% annual fee to yield an APY of roughly 6.2%. These lenders are much better off buying preferred stock or going to bankdeals and finding a bank running a certificate of deposit promotion.

(3) Ok, here's the take away... If you haven't funded your account yet, consider taking a break for about two weeks and checking back. Perhaps the supply of borrowers (with good applications) will fall in line with the current demand of lenders.

(4) Alternatively, if you're patient, go ahead and fund your account. However, if you're picky like me, you may not be able to find more than one or two decent loans a week.

I'm thinking that the groups that "vett" the loan applications are not doing a sufficient job training their loan applicants in writing a loan request. If I ran a group, i'd seriously consider trying to set a minimum interest rate based on each loan applicants credit grade. While, there probably isn't an efficient mechanism for enforcing this, i'd certainly try to steer them in the right direction. Absent of opening my own group, I whole heartedly recommend the group "due diligence." It's group leader has consistently turned out quality applicants. Let's see if he keeps it up.

Additionally, I HOPE that over time, people are going to hear about the great rates that borrowers are getting on loans and that the growth rate in borrowers may eclipse that of lenders and correct this temporary supply-demand imbalance.

Finally, prosper borrowers should consider listing their loans at their state's max interest rate. Not very many people are doing this. If done, they'll get an instant rush of bids through prosper's automated fill system. On top of that, they'll get massive click traffic for their application. Their application will pass most of the lender's initial screens. In no time, they'll have a 100% bidded loan. Then, they can sit back and watch the lenders bid the rate of the loan down like starving piranas

Good Luck All (Borrowers/Lenders)!

Watching the Stock Trades of One of the Sharpest Stock Pickers (CNBC Squawk Box Maserati Competition Winner)

Thomas Ko beat out over 150,221 investors in the CNBC Squawk Box Challenge by turning a hypothetical one million dollar portfolio into over $5 million in just six weeks.

Thomas Ko is still on a hot streak. He's matched up against 5 bonafide stock market professionals and is kicking their butt too!

Go to the MSN Strategy Lab to watch Thomas Ko's trades. Thomas Ko started with a hypothetical $100k on June 16th and has already turned it into $134,548. Part of his edge is probably the fact that he's hot and everybody is piling in, more so than the Jim Cramer (BoooYAH) fanatics.

Optimizing Money Transfer Into Your Prosper.com Account

I ran a little experiment to determine what is the best day for transferring funds into Prosper.com. I'm a Prosper lender who prefers not to have hundreds or thousands of dollars sitting in Prosper.com's 0.0% interest bearing accounts. So, I routinely do 3-5 transfers a week into my account. I look at it as just-in-time financing.

This is what I found:

(1) Transfers initiated on Sunday, Monday and Tuesday had the quickest turn-around (3 days)
(2) Transfers initiated on Thursdays had the worst turn-around (6 days)

Prosper.com states that transfers should occur within 2-4 days of initial request. I have yet to see a 2 day transfer. I suspect that my results may be varying from others in that I use a regional bank vs. a national bank. In this respect, my regional bank may be slower than some of the major national banks that Prosper.com has worked with.

My recommendation to you:

(1) Use the just-in-time financing strategy (multiple transfers during the week)

(2) Establish a baseline amount equal to (1) or (2) times your normal bid. Keep this in your Prosper account at all times. This baseline amount won't collect interest, but can be immediately used to bid on those loan requests that have the "automatic funding" feature. Some of these loans are being filled in less than 3 days. I even saw a great deal yesterday (C rating @ 18% interest rate). This request was for less than $2k and actually funded in less than 4 hours after initial posting.

(3) Transfer the bulk of your funds on Tuesdays. This way the money is in your account for the weekend, a period where no new money is added to prosper lending accounts.

Summary of my results for lending transfers (your results may vary)

Transfer Initiated / Transfer Completed
Sun / Wed (3 days)
Mon / Thur (3 days)
Tue / Fri (3 days)
Wed / Mon (5 days)
Thur / Wed (6 days)
Fri / Wed (5 days)
Sat / Wed (4 days)

I have yet to see a daily deadline for balance transfers. Does anybody know whether balance transfer requests initiated after a particular time are deferred until the next business day? If so, what's the time?

Monday, June 19, 2006

GRRRR Dish Network: I Just Forfeited a $100 Rebate (#$*&^%)

I hate rebates!!! I believe I read that only 1/2 of the people out there actually file their rebates properly. Well, count me in that group of 50% who files improperly.

In April we got a Dish Network satellite system. We skimped on paying the extra $5/month for the local channels but we splurged and got two DVR receivers (our first time to have either a DVR or satellite dish).

Anyways, upon initiating our contract we got a $100 rebate good for $10 off each month's bill for 10 months. The rebate form stated that it was valid between 2/1/2006 and 6/30/2006. Knowing that I had plenty of time (like mailing taxes on April 17th), I procrastinated until today to mail it in. MY MISTAKE. The fine print on the document says that it has to be postmarked within 60 days of account activation.... We activated the account on April 8th! Having a very Homer like moment here (DOOHHHH). Well, it's already stamped, i'm sending it out anyways. We'll see if they overlook it.

Saturday, June 17, 2006

Legit Way to Get $20 in Gift Cards of Your Choice Each Year

I just redeemed my account balance at mypoints.com for a $10 gasoline card. I've been a member of mypoints.com for roughly 4 or more years and have obtained $110+ in gift cards over this time (red lobster, starbucks, Exxon Mobil, etc).

What did I have to do? I provide them w/ an email account and they send email advertisements to my account. I read the advertisements and get 5-10 points for just reading them and 200-1000+ points for participating in particular sales promotions.

I've never had a problem with the site and would recommend it to others. If you want, send me an email and i'll do a referral. Mypoints.com has a current promotion where people referred by friends get 125 free points for their account while the person providing the referral gets 100 points.

Since becoming a member of the mypoints community, i've only participated in one promotion (getting a sharebuilder.com account). All the other points that i've obtained (16,900) have been via their email advertisements.

While I say you can get $20 in gift cards/year, there are others out there who could get over $100 per year based on shopping patterns. This combined with the use of rebate credit cards can provide you a way to double-dip on refunds/kick-backs.

Got A Blog? Let's Do a Link Exchange!

I've been blogging now since February and am looking to fill in the preferred links section of my blog. If you like my content send me an email, i'd be happy to review your site and do an exchange.

Here's some specs on my site:

(1) Technorati Rank: 210,838 (30 links from 16 sites)
(2) One of the highest rated blogs on pfblogs.org, currently hold a rating of "7+" clicks per article
(3) Now have 103 articles posted to site
(4) Successful interview at money blogger podcasts
(5) Strongest trait: I'm a finance geek!

Send link exchange requests to: pluggedinfinance(at)gmail.com

Goodbye ING Direct... Goodbye Online Gambling!

I just cashed out all but $1 from my ING Direct account. Additionally, I cashed out all but $3 from my online gaming account.

ING Direct has simply fallen behind the pack in offering competitive rates. Heck, my local credit union (Navy Federal) is offering as high a return on their money market accounts. Cashing out now also establishes a lower baseline account value in the event ING Direct tries another promotional period of offering a higher interest rate to new money.

As for gambling, I've kept to a budget; however, most games require a "rake" which shifts any game from equal odds to one that has a negative implied value (house always win). I feel that i'm better off using these new funds to boost my prosper.com bankroll in order to construct a real return portfolio that should net my family around a 12%+ real return.

So far, I've got 9 active loans (18.38% avg interest rate) with 4 going to funding and 2 in the bidding process. Short term, i'm considering keeping my loan bids around $50 or so. I'll probably start doubling my bids to $100 once our loan portfolio achieves $50/month in interest income.

Friday, June 16, 2006

Top Car Lease Scams That Dealerships May Pull On You

"The excitment of leasing a brand-new car can lead you to rush into a contract without reading the fine print. And, some unscrupulous car dealers can spot an over-excited and unsuspecting consumer from a mile away. So before you sign your name on the dotted line it's important for you to spot a leasing scam. Here are seven of those leasing scams (Source: military.com)"

As for my opinion on car leases, haven't done one yet (only buy them). However, if I did, I'd start with Costco (wholesale club) and use them for comparison shopping. Costco tends to have good deals, and i've heard favorable things about their car leases from a relative (relative got two hondas via Costco).

Wednesday, June 14, 2006

Prosper Lending Points to Ponder

I now have 8 active loans. Here's a few tips based on what I've learned to date.

(1) Check out Eric's Credit Community. This site gives a lot of good stats about Prosper lenders and borrowers. Recommend looking at his summary of delinquent loans. One limitation of this site is that some inaccuracies exist in the data that Eric presents. For example, his site lists me as having loaned out $500+ in loans. I've loaned out $377. It seems that he isn't capturing the cases where loans get bid to 100% but get pulled by the lender before Prosper transfers funds to the borrower's account. Absent of this example, much of his other data is invaluable.

If you look at the delinquent loan list, you'll find a common theme: In 79% of the late loan cases, the group leader did not participate in the bidding. If a cook doesn't eat his/her own cooking, are you confident in eating it too? I like to check for this whenever i'm bidding on loans. I typically use my own screen/filter to identify ideal loans; however, I quickly gain a little more confidence in my bid when I see that the group leader is bidding too. The group leader is typically involved in vetting loan applicants (directly or indirectly) and should have the best information to determine whether the risk vs. reward is more favorable for the lender or borrower. This approach has its limitations in that some groups state that they bid on all of their loans (watch out for this).

(2) The proper lending dead-zone occurs during the weekends. I call it a dead-zone b/c I believe that ACH transfers (money) do not occur during this time frame and there's fewer lenders able to lend when loan applications are expiring. My tip: make sure you have at least one increment of your typical bid in your account by Fridays. This way, you can participate in bidding on loan(s) when other people have less capability of bidding and competing against you.

(3) Seeing that the big money likes the same loans as me is reassuring. Right now, "L5" is the biggest lender on Prosper. After I find a loan that I like, I'm a bit more reassured when I see the big lenders, like "L5," bidding on the same loan. This third comment isn't empirically tested to determine validity. While pure conjecture, many people with wealth don't get wealthy by being dummies.

(4) It's my personal opinion that you should stay away from borrower's that are either asking for charity or have a tone similar to "help __ out," "need a break," etc.

(5) It's my personal opinion that you should not bid on business loans when the borrower's APR is greater than what you perceive is a reasoanble profit margin for them.

Feel free to scroll down to my other listings. Many of the recent ones are specific to Prosper lending.

Sunday, June 11, 2006

Read This if You Take Home The Excess Toiletries From Hotels

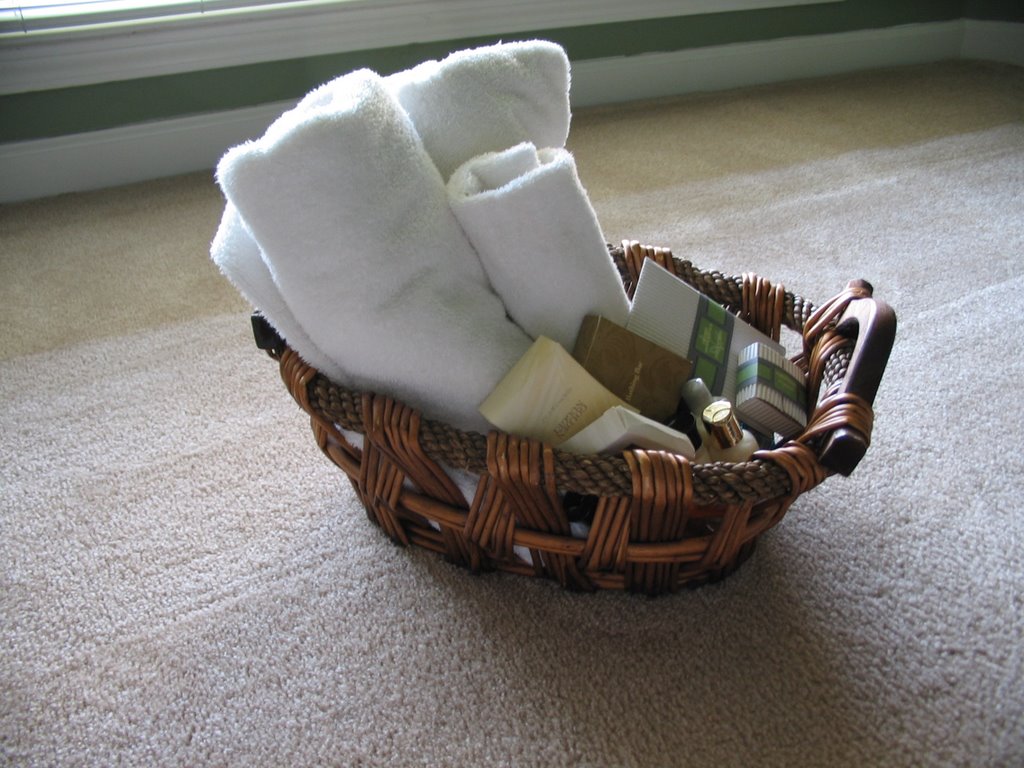
Every time we stay in a hotel, I make sure I take any excess toiletries home. The only problem is that they've been piling up in a bathroom junk drawer. Well, I came up with the following idea for our guest bathroom. I took a small basket, rolled up some of our towels and placed some of our hotel toiletry stash in the basket.


This should work well for most households. I put the best ones (lux and casino hotel toiletries) in the basket while keeping the cheaper ones for our master bath.

Saturday, June 03, 2006

An Implied Tax On Prosper Lending Portfolios: Just Realized That Prosper Pays You Less Than What You List as Your Minimum Yield on Bids

Prosper.com doesn't make money just off the "delta" between the borrowers APR and the lender's approved APR bids. There is an additional 0.5% fee charged on all loans. In addition, the group rewards don't come from the "delta" mentioned above. THEY GET DEBITED FROM PAYMENTS MADE TO THE LENDER. This is disturbing because a lender viewing the Prosper.com help section titled "FEES" (as of 3 Jun 2006) will not see anything about group rewards at all. Furthermore, Prosper.com goes to the point of saying in this specific section that "There are no other fees of any kind."

I previously inferred that they come from the "delta" between the borrower and lender's APR, now I feel a bit betrayed. However, I know realize that while Prosper should communicate this fee more effectively, it's a novel strategy to channel lenders into joining groups in order to offset this implied "group rewards" tax on loan portfolios.

I discovered all of this when I examined the performance on our first two loans. This is what I found:

(1) First loan of $50 to a "B" credit rated individual collecting 11.85%... $1.68 was paid, $0 removed as a not sufficient funds fee (NSF), $0.03 was removed as a group reward fee and $0.02 was removed as a Prosper.com fee.

(2) Second loan of $50 to an "E" credit rated individual collecting 21.50%... $1.93 paid, $0 was removed as a NSF fee and $0.05 was removed as a group reward fee and $0.02 was removed as a Prosper.com fee.

Bottom Line: $3.61 paid, $0.12 deducted (3.3% implied tax)... While the 12 cents doesn't go to federal or local governments, I view it as an implied tax. If you only look at the group reward fee, I had $0.08 removed (2.2% implied tax).

If you read the fine print in the fees section, Prosper states that the actual service fee ($0.04 of the $0.12 deducted this time) actually varies depending on the timing of the loan.

I recommend that lenders be careful and understand that your bid is actually an annual percentage rate (APR) vice an annual percentage yield (APY=what's actually deposited in your account). Your winning bid will be reduced by 0.5% or more to get your APY. Prosper.com will give you an APY in the "loan performance" section. However, I remain suspicious as to whether or not Prosper is calculating the APY correctly. It is not clear as to whether or not they are factoring in the group rewards deducted from lender disbursements to determine the actual APY. IF NOT, THEY SHOULD!!

On another note:
(1) When is PROSPER.COM going to start advertising with commercials?
(2) When is PROSPER.COM going to start offering IRA options?
(3) When is PROSPER.COM going to start paying interest on funds not invested? Come one, even brokerage firms pay a measly yield.

Please don't construe the tone of this posting as anti-PROSPER. I will continue to use it. I may have made a mistake an overlooked a disclosure that specifically addresses "group rewards" fees against disbursements. Now that I know "group rewards" get deducted from the money that is due to me (the lender), I will re-evaluate how much I value the vetting done by groups sponsoring borrowers.

Wednesday, May 24, 2006

Prosper is Now Easier To Use: Advanced Search Feature Introduced, New Loan Limits and Other Comments

Prosper has made major strides in improving its site. I discuss some of the improvements and provide recommendations on how Prosper can further improve the lending experience.

New advanced search options are now available. The advanced search includes ability/option for:

(1) Search by specific credit rating grade(s) and minimum interest rates you're willing to accept on loaned money.

(2) Setting lower and upper search values for debt-to-income ratios.

(3) Search by specific loan amounts For example, a search for loans greater than $1,000 but less than $10,001 (or other amounts) can be done.

(4) Search for only those loans that you've bid on.

(5) Setting lower and upper search boundaries for:
(a) no. of accounts now delinquent
(b) no. of delinquencies in last 7 yrs
(c) no. of public records in last 10 years
(d) no. of credit lines
(e) no. of credit inquiries in last 6 months
(f) credit history length

Don't want to fool w/ advanced search? Then you can now use the preset popular search tabs that include: loans ending soon, high-to-low interest rates, fully funded loans, high-to-low credit grades.

All of these advanced search options can also be applied to the creation of standing orders where Prosper will automatically bid for you.

Want better risk vs. reward options? Prosper has increased the interest rate caps. About 25% of the states now permit interest rates as high as 29%. Exact info can be found here.

Not sure how to manage your loan portfolio? Check out some of Prosper's webinars.

I think that Prosper.com has plenty of room for improvements:
(1) Add IRA account option. They already have an agreement with Wells Fargo, just extend it to include IRAs.

(2) Display lending groups current default rate on all loans sponsored. Default rate (%) = (number of loans in default/total no. loans sponsored)*100
- This way, lenders can better judge the quality of the vetting done by sponsoring groups.

(3) Display lending groups current percentage of loans that are > 15, 30, 60 days late in payment.

(4) ... More to follow... Getting back to bidding on some loans and watching some baseball.

Disclaimer: I'm not an employee of Prosper. Lending or borrowing on the Prosper site is at your own risk.

Sunday, May 21, 2006

Our Updated Prosper Strategy & Four Loans We're Considering Bidding On

You can read my latest posting on prosper lending here... You can always come back to the below posting.

I have made several changes to our Prosper.com lending strategy (Prosper is a peer-2-peer lending site).

(1) We have now started to loan money to those with "E" credit ratings (10% historical default risk likelihood). Before doing so, we only bid on those with no current delinquencies and positive debt-to-income ratios. Doing this will hopefully decrease the likelihood of default to something closer to 5% or better.

(2) I'm now emailing some of the prospective borrowers. This is quite effective in that a lender can get a sense from the tone of the reply as to the sincerity of the lender. Sometimes, you'll also get bonus information that you didn't even ask for.

(3) Lenders don't necessarily need to develop a spreadsheet to track their loan portfolio performance, Prosper.com has an easy interface that does it for you.

(4) Generally, I like to fund those loans that have a funding date on or after the 1st or 15th of the month (see original strategy post for definition of funding date and reason why). I now waive this requirement if the person divulges that they get paid on a weekly basis and also pass my other forms of screening.

I've funded 3 loans so far and have an open bid on another. Our first two loan payments are due on 2nd and 3rd of Jun, others due shortly thereafter. Current effective yield on loans is 18.62% (credit ratings of B, E, and E). I've found that knowing the effective yield on your portfolio influences me in the loans that I subsequently bid on. I find that an ounce of greed is involved and influences me to bid only on those loans that improve the effective yield (increases it). I must keep this emotion in check and diversify our loan portfolio risk by adding a few more loans of B and C quality.

Here's a couple of the loans that I'm watching and considering bidding on. All loans close in greater than 4 days so those of you with Prosper accounts may have chance to transfer funds and bid on them.

Loan, Current Yield, Debt Rating, Bidding Ends (note: 4 loans originally listed, I deleted two of them as they expired or were pulled by lenders)


(a) 14587, 19.50%, "C," 29 May
(b) 14419, 22.00%, "E," 28 May

Disclaimer: I don't know anything more about the borrowers than what is already available on the Prosper website. Bid at your own risk.

Tuesday, May 16, 2006

A Ton of Finance-Investment Tid-Bits (I've Returned from Blogging Sabbatical)

I'm back! Items discussed: My podcast interview, Prosper.com, discussion of commodity/oil strategy and new job

Over the last two weeks we've been settling into our new house, and I've also been getting familiar with my new job. Here's a run down of what's been going on:

(1) Completed a personal finance interview (podcast) with the "Money Blogger Podcast." In this interview I stated our net worth at $217k (first time disclosing).

(2) Bid on two more Prosper.com loans (loan 12594 and 12002). Loan 12002 is still open for bidding. Loan 12594 has closed and is awaiting funding. Ignoring these loans, my current loan portfolio (2 loans) has an effective yield of 16.68%. Once these loans close, I'll have a net yield of about 17%. Between all 4 loans I've essentially bid on two "B" and two "E" rated loan requests.
My last round of bidding was a bit more difficult bids because it appears that the quality of applicants has gone down (at least in the short term).

(3) I've liquidated some of our commodity positions, basically because they were all at or new all time highs (sell into strength, buy in to weakness philosophy).
(a) Sold all of our Gold ETF (GLD) at $70/share. Price was getting a bit lofty, have a limit order set for buying at a lower price if it gets to $65/share.
(b) Sold 35% of our position in Rio Tinto (RTP) at $252.92/share. Position was up 60% from our fall entry price of $157.86/share. Have limit order set to buy more shares if it drops substantially to low $200s.
(c) Sold 45% of our total BHP Billiton position (BHP) at $48.58/share. Shares sold represent a short term position established in wife's IRA at $43.85 on the 27th of April and sold on the 8th of May (up 10% in less than two weeks). Remaining 55% bought last August at substantially lower price. Have limit order set to buy more shares at $43.85.

(4) Started new job as an analyst in a Human Resources/Manpower shop.

(5) Made trip out of town to visit Mom for Mother's Day (drove 800 miles, got 30.5 mpg in old 6 cylinder car)

Our investment philosophy (sectors) is shaping up for a change. We haven't fully decided on the new sectors. However, I'm considering cashing out of the oil stocks/commodity ETFs a little earlier than previously planned, perhaps when oil hits something closer to $75. I was previously thinking about selling out of our these stocks when oil hits around $80. Reasons for lowering cash-out price on oil stocks/etfs are:

(A) Oil is no longer moving significantly higher when terrorist acts occur in Nigeria or even when weapons grade Uranium is found in Iran (both have been happened recently).

(B) While the US dollar is weakening, the Wall Street Journal sites marginal increases in worldwide demand for oil (1.5% year-over-year)

(C) We are moving up quickly on an election year and politicians are going to do respond to complaints about oil prices. Even if their actions have no teeth, they will affect market sentiment.

(D) Ethanol is gaining to much steam as a viable alternative and will therefore diminish growth in future oil demand

Sunday, May 07, 2006

Plugged-In-Finance's Top Nine Posts

My site is on its way to 100 unique posts (mid-nineties) now. Today, i'm presenting some of my best/most popular posts for your reading pleasure.

(1) Walmart's Disservice to Frugal America (My Trip to Walmart Today)

(2) Are You Wealthy Enough? Equation for Determining

(3) Free Money: My Opinion on 0% APR Credit Card Offers

(4) Getting Free Cable

(5) Our Household Savings Rate Taking a Hit
Since our move, our savings rate is roughly $1,000/month plus monthly equity gains in real estate. This is essentially a $4,000 cut from before our move. Reason, wife temporarily unemployed.

(6) Graphical Picture and Discussion of Our Household Investments
This graph is somewhat dated but still reasonably accurate

(7) Prosper Lending Strategy
We've done two loans so far, looking for a 3rd and 4th loan.

(8) Buying Real Estate: My Mortgage Lessons Learned

(9) Is an Education Worth the Expense

Enjoy!

Saturday, May 06, 2006

Save $20 on Your Next Dell Order

I found a $20 Dell Coupon in an unmarked Life Cereal Box. The only thing on the outside was a curious George offer for his CD. The $20 coupon states:

A Special Offer From Dell. Take $20 off any Electronics and Accessories purchase of $150 or more!* at Dell.com. Enter coupon code QGM7T0C1C2TVVD at checkout.

*Pricing, specifications, availability and terms of offers may change without notice. Taxes, fees and shipping and handling charges are extra and vary. Offer does not apply to, and is not available with systems or items purchased through online systems configurator, refurbished or spare parts. Limit five same items per order. One coupon per customer. Dell cannot be responsible for pricing or other errors, and reserves the right to cancel orders arising from such errors.

Wednesday, May 03, 2006

Avian Flu: Summary of Stock Market Sectors That Stand to Gain or Lose

Here's a simple summary of those sectors that stand to gain or lose in the event an Avian Flu outbreak occurs:

POTENTIAL WINNERS
(1) Drug companies that make antiviral medicines
(2) Drug companies that make vaccines
(3) Hospital health care
(4) Cleansing product-makers
(5) Home entertainment providers
(6) Telecommunications
(7) Internet technology companies

POTENTIAL LOSERS
(1) Airlines
(2) Luxury goods
(3) Hotels
(4) Insurers
(5) Shopping malls
(6) Major oil firms
(7) Mining and metals
(8) Travel and hospitality
(9) Brewers

SOURCE: Citibank Report as Summarized in "Wall Street Placing Bets on Bird Flu Outcomes," Chicago Tribune, Bruce Japsen, April 30, 2006

Sunday, April 30, 2006

Peer-2-Peer Lending: Changes I'd Like to See at PROSPER.COM

Bottom line: I make three recommendations as to what Prosper should do to improve the lending experience.

(1) Offer IRA option... It's increasingly important to offer pseudo real-return investment alternatives.

(2) Provide metrics to grade groups, such as:

(a) Red/green light indicator next to groups to indicate if group's portfolio of originated loans as a default rate below or above Prosper.com averages. This is important to identify whether those groups screen applicants sufficiently (Indicator lights recommended b/c they provide a quick indication. There are obviously other ways to accomplish the same goal).

(3) Improve "search loan" filter to include:

(a) Lender rates greater than or equal to (enter value)

(b) Specific borrower credit characteristics (now delinquent, number inquiries last 6 months, etc).

(c) Include only those loans with picture(s) and write-up, while this may not have a material impact, it has an impact on the screening process experience.

PROSPER.COM