Posts


I recently brought my 98 Acura to the dealership to troubleshoot my check engine light. They charged me $80 up front just to hook up there computer, download the error code and translate it for me.
It turned out that my problem was a "low flow" indication for my catalytic converter. The dealership then quoted a price of $1000 to fix the problem and then told me:
(1.) It's far cheaper to go to a muffler shop. I compared 3 shops and found one that quoted me $479 to replace all piping, catalytic converter and muffler.
(2.) You could have originally gone to Autozone and had them tell you the trouble code on the car, saving you the $80. You would then have to go home and look up the trouble code on your computer.
I looked under the car and found that I had rust holes in the piping before my catalytic converter. I think that this is the main reason for the problem. From what I understand I could probably do a $5 temp fix to patch the leak in the exhaust pipe before the converter... I can also disconnect my car battery and reset the check engine light.
Since my car is getting old (only has a trade in value of $2k), it isn't worth spending $479 to repair the problem. I'm going to default to the temp fix and will go to Autozone if the check engine light comes on again. If I can't fix the problem, I can just go to Autozone periodically to get an engine reading to see if any new error/trouble codes have cropped up.
Thursday, July 31, 2008


Buyers of 2009 VW Jetta TDI Get $1300 Tax Credit
The IRS just announced that the 2009 TDI meets its requirements for the Advanced Lean Burn Technology Motor Vehicle Credit. Buyers of a new 2009 VW Jetta TDI qualify for a $1300 tax credit.
Turns out that diesel drivers can now enjoy tax credits similar to what hybrid drivers have been getting for the past few years.
Related Car and Driver Article.
Turns out that diesel drivers can now enjoy tax credits similar to what hybrid drivers have been getting for the past few years.
Related Car and Driver Article.
Sunday, July 20, 2008
105 Hypermiling Tips
Ecomodder is an excellent site for the driver who wants to be thrifty with gas. This evening I came across a posting of 105 hypermiling tips posted on its site.
Saturday, July 19, 2008
How Can You Spend Less Money on Fuel?
This is by far the most intelligent webposting on fuel economy that i've come across. It adds a little of the science behind fuel economy. If it does not address your interests in the subject, take the time to read the cited articles at the very end.
Also, try going to youtube.com and searching for hypermile, hypermiler or hypermiling.
There are obviously more ways to save money and they include not driving, using gasbuddy.com and using gasoline credit cards.
Enjoy.
Also, try going to youtube.com and searching for hypermile, hypermiler or hypermiling.
There are obviously more ways to save money and they include not driving, using gasbuddy.com and using gasoline credit cards.
Enjoy.
41% Improvement in my Acura's MPGs
With today's gas prices, I've been thinking a bit more about practicing gas saving techniques. I have already been conservative in my driving over the past 2 years and routinely exceed EPA ratings.
Before gas prices exceeded $3/gallon, I was already:
1.) Coasting to red lights
2.) Gently accelerating about 1/2 the time. Rest of time accelerating as schedule required.
3.) Using cruise control religiously
4.) Minimizing use of brakes
Now that gas has gone "thru the roof," I've been keeping an eye out for some additional techniques.
About 2 weeks ago, I had the opportunity to drive from central Louisiana to Washington state. I'm moving my household to the Northwest and had my car loaded down with approximately 800 lbs of household goods and self.
My car is a 1998 Acura 2.3 CL, automatic. The 2.3 stands for 2.3 liter (4 cylinder). The EPA rates it at 19 city / 27 hwy. I regularly get 30-31 mpg hwy using techniques 1-4 above. However, on this trip I took one leg of my trip to test the following techniques:
5.) Observing speed limit. Basically, not exceeding it.
6.) Drafting. To minimize the danger of drafting, I kept about 1 car length distance for every 10 miles of speed. My favorite vehicles to draft were the RVs with the one-piece rock guards that went behind both sets of back tires. RVs were also more apt to maintain steady speeds on hills, as compared to 18 wheelers.
7.) Coasting in neutral down hills. This dropped my rpm from 2500-3000 rpm to about 900 rpm. Warning: This is illegal in some states and could get you hurt. The famous "click and clack" brothers who talk about cars advise against doing so.
8.) Ceased using cruise control when going up some steep hills. In doing this, I would remember my cars RPM while cruising before the hill. Once I reached the hill, I would listen for when my car was trying to apply more fuel and increase rpm. I would then immediately cease cruise control and maintain RPM vice speed. I would maintain RPM until I crested the hill. After cresting the hill, I would decide as to whether or not the downward slope was long enough to coast down or whether or not I would accelerate and reset cruise control.
Over the course of this experiment I averaged 68 mph and 37.98 mpg.
This represents an 11 mpg increase (40.7%) over my rated 27 mpg and with 800lbs of household goods in my car!
... It's about 2 weeks later now and I'm currently on travel and using a rental car. I've have / will experiment with two additional techniques with the rental car (4 cylinder Hyundai Sonata):
9.) Cutting off engine at stop lights. This mimics what hybrids already do.
This is my first time trying #9 and it's also being done in an unfamiliar area where I'm not fully aware of cycle times for red lights. It's probably best to test this on my route to work where I'm most familiar with which lights are long.
10.) Inflating tires to maximum tire pressure. I'm trying this tomorrow in a drive between Norfolk, VA and Washington D.C. I typically keep my tires at 32 psi but will try inflating them a little more after reading the manufacture's max tire pressure. Many "hypermiler" websites recommend increasing to max tire pressure. I'll raise the tire pressure somewhere between 32psi and the max pressure while leaving the pressure a tad below max pressure. Aside: my friend tried this technique with his Jetta TDI and lost one tire from tread separation (thus my reason for not going to max pressure but something close).
Before gas prices exceeded $3/gallon, I was already:
1.) Coasting to red lights
2.) Gently accelerating about 1/2 the time. Rest of time accelerating as schedule required.
3.) Using cruise control religiously
4.) Minimizing use of brakes
Now that gas has gone "thru the roof," I've been keeping an eye out for some additional techniques.
About 2 weeks ago, I had the opportunity to drive from central Louisiana to Washington state. I'm moving my household to the Northwest and had my car loaded down with approximately 800 lbs of household goods and self.
My car is a 1998 Acura 2.3 CL, automatic. The 2.3 stands for 2.3 liter (4 cylinder). The EPA rates it at 19 city / 27 hwy. I regularly get 30-31 mpg hwy using techniques 1-4 above. However, on this trip I took one leg of my trip to test the following techniques:
5.) Observing speed limit. Basically, not exceeding it.
6.) Drafting. To minimize the danger of drafting, I kept about 1 car length distance for every 10 miles of speed. My favorite vehicles to draft were the RVs with the one-piece rock guards that went behind both sets of back tires. RVs were also more apt to maintain steady speeds on hills, as compared to 18 wheelers.
7.) Coasting in neutral down hills. This dropped my rpm from 2500-3000 rpm to about 900 rpm. Warning: This is illegal in some states and could get you hurt. The famous "click and clack" brothers who talk about cars advise against doing so.
8.) Ceased using cruise control when going up some steep hills. In doing this, I would remember my cars RPM while cruising before the hill. Once I reached the hill, I would listen for when my car was trying to apply more fuel and increase rpm. I would then immediately cease cruise control and maintain RPM vice speed. I would maintain RPM until I crested the hill. After cresting the hill, I would decide as to whether or not the downward slope was long enough to coast down or whether or not I would accelerate and reset cruise control.
Over the course of this experiment I averaged 68 mph and 37.98 mpg.
This represents an 11 mpg increase (40.7%) over my rated 27 mpg and with 800lbs of household goods in my car!
... It's about 2 weeks later now and I'm currently on travel and using a rental car. I've have / will experiment with two additional techniques with the rental car (4 cylinder Hyundai Sonata):
9.) Cutting off engine at stop lights. This mimics what hybrids already do.
This is my first time trying #9 and it's also being done in an unfamiliar area where I'm not fully aware of cycle times for red lights. It's probably best to test this on my route to work where I'm most familiar with which lights are long.
10.) Inflating tires to maximum tire pressure. I'm trying this tomorrow in a drive between Norfolk, VA and Washington D.C. I typically keep my tires at 32 psi but will try inflating them a little more after reading the manufacture's max tire pressure. Many "hypermiler" websites recommend increasing to max tire pressure. I'll raise the tire pressure somewhere between 32psi and the max pressure while leaving the pressure a tad below max pressure. Aside: my friend tried this technique with his Jetta TDI and lost one tire from tread separation (thus my reason for not going to max pressure but something close).
Friday, July 18, 2008
BMW: 59 MPG / 0 to 60 in 8.8 sec
BMW brought its 118d not for sale in U.S. diesel to New York City to accept the 2008 World Green Car Award.
It's a bit disappointing that BMW isn't selling this car in the U.S.. It's also more disappointing that the legislature is not more aggressive with our Nations' energy policy to promote cars like this. Sort of makes me think that Congress would much rather prefer low-economy cars so that they generate more income from fuel taxes.
Here's the link.
It's a bit disappointing that BMW isn't selling this car in the U.S.. It's also more disappointing that the legislature is not more aggressive with our Nations' energy policy to promote cars like this. Sort of makes me think that Congress would much rather prefer low-economy cars so that they generate more income from fuel taxes.
Here's the link.
Monday, February 04, 2008
ZERO / LOW COST METHOD FOR LONG TERM INVESTING IN 5 STAR RATED COMPANIES
Read this if you are interested in establishing no/low cost long term investments via DRIPS.
I own 23 DRIPS and strongly believe in using them as a component of a diversified portfolio. I like DRIPS because of their low cost method of investing. I also find them useful in that they force you to buy and hold (not as liquid as stocks in regular brokerage account).
There are several useful sites for DRIP investors. They are:
(1.) Moneypaper INC's DIRECTinvesting.com
(2.) Computershare
(3.) Bank of New York-Mellon
(4.) Mellon Bank (in process of merging w/ "3" above)
(5.) Wells Fargo
The Moneypaper is a great starting point to find out what holding company carries the DRIP you are interested in. Then, you can either go to their website and buy, or purchase through the Moneypaper if the holding company does not allow direct initial purchase.
The title alludes to 5 star rated companies. I did a search on my Morningstar account for 5 star rated (highest Morningstar rating) DRIPS then compared it against the Moneypaper's no/low cost list. Morningstar's ratings are dynamic and change periodically when staff updates a stock's analysis. When I say no/low cost, I mean zero or negligible fees for dividend reinvestment, auto-purchase or cash purchase. Here's the result:
Finance
Bank of America
Capital One
Cathay General Bancorp
Comerica Inc
Regions Financial
Morgan Stanley
Synovus Financial
Wachovia
Wilmington Trust
REIT
Brandywine Realty Trust
CapitalSource Inc
Corporate Office Properties
DRUGS
Johnson & Johnson
Mylan Laboratories
Schering-Plough
Valeant Pharmaceuticals
Natural Resources
Alumina
Marathon Oil
Southern Union
Discretionary
Anheuser-Busch
Brown-Forman
General Mills
Kellogg Company
Limited Brands
Wal-Mart
Other
3M
Boeing
Consolidated Edison
Graco
ITT Corp
Masco
McGraw-Hill
Paychex
Of the companies listed, I own McGraw Hill, 3M, Graco, Wal-Mart, Limited Brands, Anheuser-Busch, Johnson & Johnson & Bank of America via DRIPS. I've been eyeing Boeing. I own Alcoa, Baker Hughes and Exxon DRIPS for exposure to Natural resources, but would also consider Apache. I own the Southern Company DRIP for exposure to utilities. In lieu of some of the industrials above, I own the Manitowac, Pentair and Cummins DRIPS. I've been avoiding the food stocks and have instead gone long Agriculture via ADM and JJG (ADM and JJG not via DRIPS).
Aside: My employer provides us with a free subscription to Morningstar. If you don't already have access, you can frequently find Value-line and Morningstar at your local library.
I own 23 DRIPS and strongly believe in using them as a component of a diversified portfolio. I like DRIPS because of their low cost method of investing. I also find them useful in that they force you to buy and hold (not as liquid as stocks in regular brokerage account).
There are several useful sites for DRIP investors. They are:
(1.) Moneypaper INC's DIRECTinvesting.com
(2.) Computershare
(3.) Bank of New York-Mellon
(4.) Mellon Bank (in process of merging w/ "3" above)
(5.) Wells Fargo
The Moneypaper is a great starting point to find out what holding company carries the DRIP you are interested in. Then, you can either go to their website and buy, or purchase through the Moneypaper if the holding company does not allow direct initial purchase.
The title alludes to 5 star rated companies. I did a search on my Morningstar account for 5 star rated (highest Morningstar rating) DRIPS then compared it against the Moneypaper's no/low cost list. Morningstar's ratings are dynamic and change periodically when staff updates a stock's analysis. When I say no/low cost, I mean zero or negligible fees for dividend reinvestment, auto-purchase or cash purchase. Here's the result:
Finance
Bank of America
Capital One
Cathay General Bancorp
Comerica Inc
Regions Financial
Morgan Stanley
Synovus Financial
Wachovia
Wilmington Trust
REIT
Brandywine Realty Trust
CapitalSource Inc
Corporate Office Properties
DRUGS
Johnson & Johnson
Mylan Laboratories
Schering-Plough
Valeant Pharmaceuticals
Natural Resources
Alumina
Marathon Oil
Southern Union
Discretionary
Anheuser-Busch
Brown-Forman
General Mills
Kellogg Company
Limited Brands
Wal-Mart
Other
3M
Boeing
Consolidated Edison
Graco
ITT Corp
Masco
McGraw-Hill
Paychex
Of the companies listed, I own McGraw Hill, 3M, Graco, Wal-Mart, Limited Brands, Anheuser-Busch, Johnson & Johnson & Bank of America via DRIPS. I've been eyeing Boeing. I own Alcoa, Baker Hughes and Exxon DRIPS for exposure to Natural resources, but would also consider Apache. I own the Southern Company DRIP for exposure to utilities. In lieu of some of the industrials above, I own the Manitowac, Pentair and Cummins DRIPS. I've been avoiding the food stocks and have instead gone long Agriculture via ADM and JJG (ADM and JJG not via DRIPS).
Aside: My employer provides us with a free subscription to Morningstar. If you don't already have access, you can frequently find Value-line and Morningstar at your local library.
Monday, January 21, 2008
U.S. Stock Market Crash Prevention Mechanisms
Watching the European and Asian stock markets plunge this Monday and Tuesday (their time) prompted me to research what mechanisms are in place to prevent a market crash here in the U.S.
According to about.com the following mechanisms are in place:
- The market will halt trading for an hour if the Dow drops 10% before 2 pm.
- Trading will halt for two hours if there is a 20% drop in the Dow before 2 pm.
- If the Dow drops 30%, trading is halted for the day.
DOW futures are pointing to a 5%+ drop tomorrow morning. This is coming at the heels of market drops around 7-10% overseas.
According to about.com the following mechanisms are in place:
- The market will halt trading for an hour if the Dow drops 10% before 2 pm.
- Trading will halt for two hours if there is a 20% drop in the Dow before 2 pm.
- If the Dow drops 30%, trading is halted for the day.
DOW futures are pointing to a 5%+ drop tomorrow morning. This is coming at the heels of market drops around 7-10% overseas.
I'm Back to Personal Finance Blogging
In the coming days I will start posting new content. During my time away from blogging I finished 13 months of training and deployed time in Afghanistan. In hindsight the tour was very rewarding.
In the coming weeks I will get back to posting on topics related to:
1.) Our recent purchase of a used car via ebay
2.) Our prosper.com loan portfolio
3.) Our new dividend reinvestment plans
4.) What we're doing with our other investments.
If I were you, I'd keep my eyes tuned to tomorrow's stock market. It's likely to gap lower significantly. We've been in bonds, for the most part, since mid December and have also enjoyed some gains shorting the market. I'm seriously considering dipping my toes into the market this week if Monday's Asian & European market bloodbaths (i.e. German DAX down 6% on Monday alone) continue with the U.S. on Tuesday.
In the coming weeks I will get back to posting on topics related to:
1.) Our recent purchase of a used car via ebay
2.) Our prosper.com loan portfolio
3.) Our new dividend reinvestment plans
4.) What we're doing with our other investments.
If I were you, I'd keep my eyes tuned to tomorrow's stock market. It's likely to gap lower significantly. We've been in bonds, for the most part, since mid December and have also enjoyed some gains shorting the market. I'm seriously considering dipping my toes into the market this week if Monday's Asian & European market bloodbaths (i.e. German DAX down 6% on Monday alone) continue with the U.S. on Tuesday.
Monday, March 05, 2007
CNBC Million Dollar ($) Portfolio Challenge Trivia Questions
I intend to post the answers to as many of the CNBC portfolio challenge questions as possible. Triva Q/A will be in the comments section of this posting.
For answers to the 2008-2009 Million Dollar Portfolio Challenge click here.
For answers to the 2008-2009 Million Dollar Portfolio Challenge click here.
Saturday, March 03, 2007
Adding to Four Dividend Reinvestment Plan (DRIP) Holdings
Before deploying to Afghanistan, I stopped my automatic purchase plan in all of my DRIPS. I felt that the stock market had run it's course and I wanted to keep new money on the sidelines. Now, the broad market sell off has created a buying opportunity. I'm not saying that the market is done going down. However, I feel that a person can cherry-pick from the listed securities to find some safe bets. Plus, in DRIPS, I frequently make small purchase which in itself is somewhat forgiving if the market goes down further.
I'm adding to my position in the following DRIPS:
3M (MMM)
Johnson & Johnson (JNJ)
Bank of America (BAC)
Budweiser (BUD)
I have a free subscription to Morningstar.com thru my employer. I frequently use Moringstar and Yahoo Finance to find suitable value stocks. Based on Morningstar/Yahoo Finance, I feel that the above stocks are at least 25% below their intrinsic value.
The additional beauty of the above stocks is that I already have DRIPS in them and my subsequent purchases cost $0.
My other DRIP positions are (Lowes, Yahoo and Home Depot have DRIP fees):
Exxon Mobil (XOM)
Lowes (LOW)
Yahoo (YHOO)
Home Depot (HD)
Southern Company (SO)
Aflac (AFL)
I'm adding to my position in the following DRIPS:
3M (MMM)
Johnson & Johnson (JNJ)
Bank of America (BAC)
Budweiser (BUD)
I have a free subscription to Morningstar.com thru my employer. I frequently use Moringstar and Yahoo Finance to find suitable value stocks. Based on Morningstar/Yahoo Finance, I feel that the above stocks are at least 25% below their intrinsic value.
The additional beauty of the above stocks is that I already have DRIPS in them and my subsequent purchases cost $0.
My other DRIP positions are (Lowes, Yahoo and Home Depot have DRIP fees):
Exxon Mobil (XOM)
Lowes (LOW)
Yahoo (YHOO)
Home Depot (HD)
Southern Company (SO)
Aflac (AFL)
Making Investment Decisions by Cherrypicking What Warren Buffett Owns
The "seekingalpha" website recently ran an article about mimicking Warren Buffet's investment decisions. This article is the first one i've seen that succinctly summarizes all of Warren Buffet's holdings.
The article is from Feb '07. Thus, some of the info is a little dated. For instance, I think Warren Buffett has already sold his Target shares.
The article is from Feb '07. Thus, some of the info is a little dated. For instance, I think Warren Buffett has already sold his Target shares.
If You Like Sharebuilder.com, You'll Probably Like This Lower Cost Rival
I stumbled on the following microvest website today. It offers $3 real time limit orders and no annual cost. It also offers $2 and $1.5 trades if you pay a monthly fee.
The website is called sogoinvest. I'm not a user of the site. I'm considering converting over my sharebuilder account. Meanwhile, i'm also considering converting my scottrade account over to tradeking.com.
The website is called sogoinvest. I'm not a user of the site. I'm considering converting over my sharebuilder account. Meanwhile, i'm also considering converting my scottrade account over to tradeking.com.
Friday, January 26, 2007
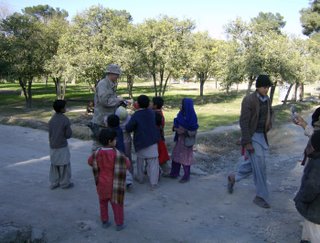
Pictures of Me Handing Out Candy to Afghan Children
I'm in Afghanistan for about another 10 months. I take great joy in handing out things to the local kids. Here's a couple of pictures of me handing out candy.
If anybody can support me with care packages, i'd love to hand out stuff for you. I'm specifically interested in getting school supplies. Anything sent would be greatly appreciated and I would be happy to take pictures for you.
Email me if interested and i'll forward you a mailing address.
Many thanks.

If anybody can support me with care packages, i'd love to hand out stuff for you. I'm specifically interested in getting school supplies. Anything sent would be greatly appreciated and I would be happy to take pictures for you.
Email me if interested and i'll forward you a mailing address.
Many thanks.
Monday, December 11, 2006
How I Got a $14,900 Annual Pay Raise
In my last post I mentioned that I was drafted (sort of). Well, everybody in the military gets a bump in their income when serving in a combat zone. While in Afghanistan, I qualify for an equivalent pay raise of $14,900 for my 12 months here.
The way it's broken down is:
Family separation Pay: $250/month
Imminent Danger Pay: $225/month
Hazardous Duty Pay: $150/month
Per Diem: $105/month
No Federal Income Tax: $326/month
Free Food: $187/month
Total: $1243/month or $14916/year
Of course, i'd give this all back for being back home.
I'm planning on using this extra money to help pay off two 401k loans that I took out for a down payment on our primary residence and the purchase of an AC system for a rental property.
The way it's broken down is:
Family separation Pay: $250/month
Imminent Danger Pay: $225/month
Hazardous Duty Pay: $150/month
Per Diem: $105/month
No Federal Income Tax: $326/month
Free Food: $187/month
Total: $1243/month or $14916/year
Of course, i'd give this all back for being back home.
I'm planning on using this extra money to help pay off two 401k loans that I took out for a down payment on our primary residence and the purchase of an AC system for a rental property.
Saturday, December 09, 2006
I've Been Drafted (By Military), Well Sort Of
I've been a bit quiet lately because I've been going through a fairly turbulent process. I'm already active duty Navy, but in September of this year, I started the "individual augmentee" (IA) process. IAs are essentially piece meal replacements that go over to Iraq, Afghanistan, etc and assume Army staff jobs so that the over-worked Army can free up soldiers for actual missions.
In my title, I said drafted b/c I did not volunteer for my current assignment. Once notified, my current command and I were given 30 days notice to transfer my prior duties to others at work and for me to get ready to deploy for 12 months. In October, I finished two months of preparatory training which basically taught how to be an infantry grunt. I'm a Human Resources officer in the Navy, talk about 180 degrees out...
During my training, I was in charge of a group of 14 people. We finished the training unscathed and way ahead of schedule. Now I'm an Officer in Charge of a small unit in Afghanistan.
As for my on year tour: one month completed - eleven more to go.
As for my blog: I'm starting to settle in over here and am hoping for continued access to computers/internet. I'm still bidding on Prosper.com loans; however, i've scaled back to simply reinvesting interest income. On December 1st, I had about $5000 in Prosper loans. I'm going to watch it grow for a period of time without any new deposits. During this period, I plan on bidding predominately on loans w/ interest rates in excess of 21%. You can watch my portfolio at Erics Credit Community.
Why am I scaling back w/ Prosper.com? The main reason is to increase my liquid cash reserves, pay off two 401k loans and participate in a 10% military savings account program. I plan on working towards an eventual goal of 20% of our networth in Prosper. This goal will be reached in years not months. I intend to wait for Prosper to be in the black, financially, before I commit substantially larger sums.
As for my prosper loan portfolio performance:
- 104 loans
- 3 late (while I hate this, i'm still better than the average prosper portfolio)
- Average interest = 21.1%
- ROI = 14.96%
In my title, I said drafted b/c I did not volunteer for my current assignment. Once notified, my current command and I were given 30 days notice to transfer my prior duties to others at work and for me to get ready to deploy for 12 months. In October, I finished two months of preparatory training which basically taught how to be an infantry grunt. I'm a Human Resources officer in the Navy, talk about 180 degrees out...
During my training, I was in charge of a group of 14 people. We finished the training unscathed and way ahead of schedule. Now I'm an Officer in Charge of a small unit in Afghanistan.
As for my on year tour: one month completed - eleven more to go.
As for my blog: I'm starting to settle in over here and am hoping for continued access to computers/internet. I'm still bidding on Prosper.com loans; however, i've scaled back to simply reinvesting interest income. On December 1st, I had about $5000 in Prosper loans. I'm going to watch it grow for a period of time without any new deposits. During this period, I plan on bidding predominately on loans w/ interest rates in excess of 21%. You can watch my portfolio at Erics Credit Community.
Why am I scaling back w/ Prosper.com? The main reason is to increase my liquid cash reserves, pay off two 401k loans and participate in a 10% military savings account program. I plan on working towards an eventual goal of 20% of our networth in Prosper. This goal will be reached in years not months. I intend to wait for Prosper to be in the black, financially, before I commit substantially larger sums.
As for my prosper loan portfolio performance:
- 104 loans
- 3 late (while I hate this, i'm still better than the average prosper portfolio)
- Average interest = 21.1%
- ROI = 14.96%
Friday, November 17, 2006
Hello From The Middle East
I'm almost done w/ my traveling... I'm finally in a place that doesn't block out blogger.com.
Wednesday, November 08, 2006
On Travel
Heading overseas for a bit. Will be in the air and/or without internet for about 2 days minimum.
Tuesday, November 07, 2006
Updated Prosper Lending Strategy (A Collection of Tips)
You can read my latest posting on prosper lending here... You can always come back to the below posting.
Bottom line: I've been lending money on Prosper.com since Apr 2006. Over this time, I've developed a preferred lending style that is discussed below. Some of the tips have already been discussed piece-meal on this blog; however, I feel that it's important to now summarize them in one entry.
Bidding:
(a) Bid 0% on auto funded loans. Reason: Auto-fund loan requests still have the bid-down feature that allows the last bidder (person who first gets loan to 100%) to set a lower interest rate and bump off others who set their lending rates to the borrower's requested rate. If you set your lending rate at 0%, nobody will underbid you. Of course, if everybody bids 0%, then you'll make no money. I'm assuming that at least one person will always bid the borrower's requested rate and thereby prevent the loan from getting bid down to 0%.
(b) Don't unnecessarily tie up your money in bids at the 5-9 day mark on loan requests. The lender's rate will frequently get bid down anyways. It's typically best to bid within 48hrs or less of the loan's closing. There's one exception: Borrowers have the option to accept the current market rate whenever their loan is at 100% funding, regardless of whether it's the 9th or 2nd day of the listing. In these cases, the borrower is either desperate for the money or doesn't have the sense to let the loan get bid down further. Lenders beware! You can get some sweet returns but may be incurring additional risk.
(c) Always ensure you have enough money in your account for at least one bid on the weekend. Reason: Deposits don't get credited to lender's accounts on weekends. This is the lending/borrowing dead zone. You will get less bidding competition on the weekends. Thus, you can potentially lock in some sweeter risk-reward loans if only you have the money to lend.
(d) Don't be scared to bid on loan requests that do not have the bank account verified. Prosper cannot let a loan go to funding until the account is verified. You may tie up your money a few extra days; however, you typically get higher interest rates on these loans.
(e) Don't have your Prosper sixth sense yet? Don't know how to read people. Recommend you review various lender portfolios at Eric's Credit Community. Eric scrapes data from the Prosper website and creates useful borrower and lender stats.
- Lender Stats Table (Ranks lenders by ROI and $ invested to include their bids and holdings)
- Delinquent loans (sorted by group sponsored and non-group sponsored) If you review these, you'll start to develop your Prosper lending 6th sense. You'll also find a few lenders where you favor their lending style thereby allowing you to follow their bids.
(f) Group sponsored loans have a unique feature (sometimes). I prefer to bid on loans where the group leader bids prior to me. That shows me that he/she has confidence in the borrower and feels that the borrower presents a decent risk-reward. Warning: Some group leaders (GL's) autobid on loans for their group. This has less value to me. In these cases I still view the loans favorably. However, I bid w/ narrower % rate spreads b/c I'm somewhat suspicious of the quality of the vetting. Using narrow % rate spreads also allows the lender to more easily bail out of a loan when they see that the GL is no longer bidding. By doing this you have more control and can take action when you see that the GL no longer feels that the loan market rate provides a suitable risk-reward proposition.
(g) Use the "I buy ugly houses" lending strategy to get superior risk-reward loans. Here's my post on the strategy.
(h) In my humble opinion, the following credit grades are roughly equal: AA, A, B, C, D. If you look at Prosper loan performance data, the delinquency rates on these loans all fall within a range of 3-4%. These are very narrow delinquency rates. Thus, you must ask yourself why not bid on the "D" rated individual? You only have an additional 1% (est.) credit late/default risk but roughly an 8% greater interest rate.
(i) The key to identifying and bidding on any loan is looking for what I consider an inflection point. Has the person turned the corner from a credit disaster and is well on their way to financial bliss? Or, are they an "AA" rated individual with a $7600/month mortgage note in California and have depleted their savings?
(j) Consider the implications of the pictures or the absence thereof. Also consider whether or not their decision to autofund is based on desperation or some other reason. For further comments see my postings on the subject (posting one, posting two). Warning: Postings "one" and "two" are not necessarily ground truth. They’re merely observations with an element of conjecture thrown in.
Money Management:
(a) Don't make large lump sum deposits into your Prosper account. Doing so only precludes you from collecting interest on that money in your banking account. Instead it's best to make multiple transfers each week. Keep in mind that 3pm PST is the deadline for submitting transfer requests. Requests submitted after this time incur an extra day of processing.
(b) To get an idea of the best time for bank transfers, you may want to read my post on the subject.
(c) For Small Budget Lenders: If you have a small budget, you can make deposits of as little as $25 (recently reduced from $50). Recommend making $25 deposits when your cash balance and payments in transit add up to $25. This will allow you to have a full $50 to bid in about four or five days.
Groups:
(a) Don't join a group unless you have a need to borrow money. You cannot get any of the group rewards as a lender.
Advanced Search Filters:
(a) Recommend you set up loan search filters in roughly the same manner I outline in paragraph "3" of the following tips post. I still follow the filter strategy mentioned in this post with one main exception. I now bid on loans with DTI's as high as 60% if:
1) they rent
2) their spouse or life mate contributes significantly to household expenses
3) they own or owe on a mortgage but have significant equity (50% or better) that can be tapped in an emergency.
Bottom line: I've been lending money on Prosper.com since Apr 2006. Over this time, I've developed a preferred lending style that is discussed below. Some of the tips have already been discussed piece-meal on this blog; however, I feel that it's important to now summarize them in one entry.
Bidding:
(a) Bid 0% on auto funded loans. Reason: Auto-fund loan requests still have the bid-down feature that allows the last bidder (person who first gets loan to 100%) to set a lower interest rate and bump off others who set their lending rates to the borrower's requested rate. If you set your lending rate at 0%, nobody will underbid you. Of course, if everybody bids 0%, then you'll make no money. I'm assuming that at least one person will always bid the borrower's requested rate and thereby prevent the loan from getting bid down to 0%.
(b) Don't unnecessarily tie up your money in bids at the 5-9 day mark on loan requests. The lender's rate will frequently get bid down anyways. It's typically best to bid within 48hrs or less of the loan's closing. There's one exception: Borrowers have the option to accept the current market rate whenever their loan is at 100% funding, regardless of whether it's the 9th or 2nd day of the listing. In these cases, the borrower is either desperate for the money or doesn't have the sense to let the loan get bid down further. Lenders beware! You can get some sweet returns but may be incurring additional risk.
(c) Always ensure you have enough money in your account for at least one bid on the weekend. Reason: Deposits don't get credited to lender's accounts on weekends. This is the lending/borrowing dead zone. You will get less bidding competition on the weekends. Thus, you can potentially lock in some sweeter risk-reward loans if only you have the money to lend.
(d) Don't be scared to bid on loan requests that do not have the bank account verified. Prosper cannot let a loan go to funding until the account is verified. You may tie up your money a few extra days; however, you typically get higher interest rates on these loans.
(e) Don't have your Prosper sixth sense yet? Don't know how to read people. Recommend you review various lender portfolios at Eric's Credit Community. Eric scrapes data from the Prosper website and creates useful borrower and lender stats.
- Lender Stats Table (Ranks lenders by ROI and $ invested to include their bids and holdings)
- Delinquent loans (sorted by group sponsored and non-group sponsored) If you review these, you'll start to develop your Prosper lending 6th sense. You'll also find a few lenders where you favor their lending style thereby allowing you to follow their bids.
(f) Group sponsored loans have a unique feature (sometimes). I prefer to bid on loans where the group leader bids prior to me. That shows me that he/she has confidence in the borrower and feels that the borrower presents a decent risk-reward. Warning: Some group leaders (GL's) autobid on loans for their group. This has less value to me. In these cases I still view the loans favorably. However, I bid w/ narrower % rate spreads b/c I'm somewhat suspicious of the quality of the vetting. Using narrow % rate spreads also allows the lender to more easily bail out of a loan when they see that the GL is no longer bidding. By doing this you have more control and can take action when you see that the GL no longer feels that the loan market rate provides a suitable risk-reward proposition.
(g) Use the "I buy ugly houses" lending strategy to get superior risk-reward loans. Here's my post on the strategy.
(h) In my humble opinion, the following credit grades are roughly equal: AA, A, B, C, D. If you look at Prosper loan performance data, the delinquency rates on these loans all fall within a range of 3-4%. These are very narrow delinquency rates. Thus, you must ask yourself why not bid on the "D" rated individual? You only have an additional 1% (est.) credit late/default risk but roughly an 8% greater interest rate.
(i) The key to identifying and bidding on any loan is looking for what I consider an inflection point. Has the person turned the corner from a credit disaster and is well on their way to financial bliss? Or, are they an "AA" rated individual with a $7600/month mortgage note in California and have depleted their savings?
(j) Consider the implications of the pictures or the absence thereof. Also consider whether or not their decision to autofund is based on desperation or some other reason. For further comments see my postings on the subject (posting one, posting two). Warning: Postings "one" and "two" are not necessarily ground truth. They’re merely observations with an element of conjecture thrown in.
Money Management:
(a) Don't make large lump sum deposits into your Prosper account. Doing so only precludes you from collecting interest on that money in your banking account. Instead it's best to make multiple transfers each week. Keep in mind that 3pm PST is the deadline for submitting transfer requests. Requests submitted after this time incur an extra day of processing.
(b) To get an idea of the best time for bank transfers, you may want to read my post on the subject.
(c) For Small Budget Lenders: If you have a small budget, you can make deposits of as little as $25 (recently reduced from $50). Recommend making $25 deposits when your cash balance and payments in transit add up to $25. This will allow you to have a full $50 to bid in about four or five days.
Groups:
(a) Don't join a group unless you have a need to borrow money. You cannot get any of the group rewards as a lender.
Advanced Search Filters:
(a) Recommend you set up loan search filters in roughly the same manner I outline in paragraph "3" of the following tips post. I still follow the filter strategy mentioned in this post with one main exception. I now bid on loans with DTI's as high as 60% if:
1) they rent
2) their spouse or life mate contributes significantly to household expenses
3) they own or owe on a mortgage but have significant equity (50% or better) that can be tapped in an emergency.
Updated Prosper Lending Tips (A Summarized Collection of Topics)
You can read my latest posting about prosper here... You can always come to this 2006 posting later.
Bottom line: I've been lending money on Prosper.com since Apr 2006. Over this time, I've developed a preferred lending style that is discussed below. Some of the tips have already been discussed piece-meal on this blog; however, I feel that it's important to now summarize them in one entry.
Bidding:
(a) Bid 0% on auto funded loans. Reason: Auto-fund loan requests still have the bid-down feature that allows the last bidder (person who first gets loan to 100%) to set a lower interest rate and bump off others who set their lending rates to the borrower's requested rate. If you set your lending rate at 0%, nobody will underbid you. Of course, if everybody bids 0%, then you'll make no money. I'm assuming that at least one person will always bid the borrower's requested rate and thereby prevent the loan from getting bid down to 0%.
(b) Don't unnecessarily tie up your money in bids at the 5-9 day mark on loan requests. The lender's rate will frequently get bid down anyways. It's typically best to bid within 48hrs or less of the loan's closing. There's one exception: Borrowers have the option to accept the current market rate whenever their loan is at 100% funding, regardless of whether it's the 9th or 2nd day of the listing. In these cases, the borrower is either desperate for the money or doesn't have the sense to let the loan get bid down further. Lenders beware! You can get some sweet returns but may be incurring additional risk.
(c) Always ensure you have enough money in your account for at least one bid on the weekend. Reason: Deposits don't get credited to lender's accounts on weekends. This is the lending/borrowing dead zone. You will get less bidding competition on the weekends. Thus, you can potentially lock in some sweeter risk-reward loans if only you have the money to lend.
(d) Don't be scared to bid on loan requests that do not have the bank account verified. Prosper cannot let a loan go to funding until the account is verified. You may tie up your money a few extra days; however, you typically get higher interest rates on these loans.
(e) Don't have your Prosper sixth sense yet? Don't know how to read people. Recommend you review various lender portfolios at Eric's Credit Community. Eric scrapes data from the Prosper website and creates useful borrower and lender stats.
- Lender Stats Table (Ranks lenders by ROI and $ invested to include their bids and holdings)
- Delinquent loans (sorted by group sponsored and non-group sponsored)
If you review these, you'll start to develop your Prosper lending 6th sense. You'll also find a few lenders where you favor their lending style thereby allowing you to follow their bids.
(f) Group sponsored loans have a unique feature (sometimes). I prefer to bid on loans where the group leader bids prior to me. That shows me that he/she has confidence in the borrower and feels that the borrower presents a decent risk-reward. Warning: Some group leaders (GL's) autobid on loans for their group. This has less value to me. In these cases I still view the loans favorably. However, I bid w/ narrower % rate spreads b/c I'm somewhat suspicious of the quality of the vetting. Using narrow % rate spreads also allows the lender to more easily bail out of a loan when they see that the GL is no longer bidding. By doing this you have more control and can take action when you see that the GL no longer feels that the loan market rate is no longer a suitable risk-reward proposition.
(g) Use the "I buy ugly houses" lending strategy to get superior risk-reward loans. Here's my post on the strategy.
(h) In my humble opinion, the following credit grades are roughly equal: AA, A, B, C, D. If you look at each Prosper loan performance data. The delinquency rates on these loans all fall within a range of 3-4%. These are very narrow delinquency rates. Thus, you must ask yourself why not bid on the "D" rated individual. You only have a 1% (est.) credit default risk but a roughly an 8% greater interest rate.
(i) The key to identifying and bidding on any loan is looking for what I consider an inflection point. Has the person turned the corner from a credit disaster and is well on their way to financial bliss. Or, are they an "AA" rated individual with a $7600/month mortgage note in California and have depleted their savings?
(j) Consider the implications of the pictures or the absence thereof. Also consider whether or not their decision to autofund is based on desperation or some other reason. For further comments see my postings on the subject (posting one, posting two). Warning: Postings "one" and "two" are not necessarily ground truth. They’re merely observations with an element of conjecture thrown in.
Money Management:
(a) Don't make large lump sum deposits into your Prosper account. Doing so only precludes you from collecting interest on that money in your banking account. Instead it's best to making multiple transfers each week. Keep in mind that 3pm PST is the deadline for submitting transfer requests. Requests submitted after this time incurs an extra day of processing.
(b) To get an idea of the best time for bank transfers, you may want to read my post on the subject.
(c) For Small Budget Lenders: If you have a small budget, you can make deposits of as little as $25 (recently reduced from $50). Recommend making $25 deposits when your cash balance and payments in transit add up to $25. This will allow you to have a full $50 to bid in about four or five days.
Groups:
(a) Don't join a group unless you have a need to borrow money. You can get any of the group rewards as a lender.
Advanced Search Filters:
(a) Recommend you set up loan search filters in roughly the same manner I outline in paragraph "3" of the following tips post. I still follow the filter strategy mentioned in this post with one main exception. I now bid on loans with DTI's as high as 60% if:
1) they rent
2) their spouse or life mate contributes significantly to household expenses
3) they own or owe on a mortgage but have significant equity (50% or better) that can be tapped in an emergency.
Bottom line: I've been lending money on Prosper.com since Apr 2006. Over this time, I've developed a preferred lending style that is discussed below. Some of the tips have already been discussed piece-meal on this blog; however, I feel that it's important to now summarize them in one entry.
Bidding:
(a) Bid 0% on auto funded loans. Reason: Auto-fund loan requests still have the bid-down feature that allows the last bidder (person who first gets loan to 100%) to set a lower interest rate and bump off others who set their lending rates to the borrower's requested rate. If you set your lending rate at 0%, nobody will underbid you. Of course, if everybody bids 0%, then you'll make no money. I'm assuming that at least one person will always bid the borrower's requested rate and thereby prevent the loan from getting bid down to 0%.
(b) Don't unnecessarily tie up your money in bids at the 5-9 day mark on loan requests. The lender's rate will frequently get bid down anyways. It's typically best to bid within 48hrs or less of the loan's closing. There's one exception: Borrowers have the option to accept the current market rate whenever their loan is at 100% funding, regardless of whether it's the 9th or 2nd day of the listing. In these cases, the borrower is either desperate for the money or doesn't have the sense to let the loan get bid down further. Lenders beware! You can get some sweet returns but may be incurring additional risk.
(c) Always ensure you have enough money in your account for at least one bid on the weekend. Reason: Deposits don't get credited to lender's accounts on weekends. This is the lending/borrowing dead zone. You will get less bidding competition on the weekends. Thus, you can potentially lock in some sweeter risk-reward loans if only you have the money to lend.
(d) Don't be scared to bid on loan requests that do not have the bank account verified. Prosper cannot let a loan go to funding until the account is verified. You may tie up your money a few extra days; however, you typically get higher interest rates on these loans.
(e) Don't have your Prosper sixth sense yet? Don't know how to read people. Recommend you review various lender portfolios at Eric's Credit Community. Eric scrapes data from the Prosper website and creates useful borrower and lender stats.
- Lender Stats Table (Ranks lenders by ROI and $ invested to include their bids and holdings)
- Delinquent loans (sorted by group sponsored and non-group sponsored)
If you review these, you'll start to develop your Prosper lending 6th sense. You'll also find a few lenders where you favor their lending style thereby allowing you to follow their bids.
(f) Group sponsored loans have a unique feature (sometimes). I prefer to bid on loans where the group leader bids prior to me. That shows me that he/she has confidence in the borrower and feels that the borrower presents a decent risk-reward. Warning: Some group leaders (GL's) autobid on loans for their group. This has less value to me. In these cases I still view the loans favorably. However, I bid w/ narrower % rate spreads b/c I'm somewhat suspicious of the quality of the vetting. Using narrow % rate spreads also allows the lender to more easily bail out of a loan when they see that the GL is no longer bidding. By doing this you have more control and can take action when you see that the GL no longer feels that the loan market rate is no longer a suitable risk-reward proposition.
(g) Use the "I buy ugly houses" lending strategy to get superior risk-reward loans. Here's my post on the strategy.
(h) In my humble opinion, the following credit grades are roughly equal: AA, A, B, C, D. If you look at each Prosper loan performance data. The delinquency rates on these loans all fall within a range of 3-4%. These are very narrow delinquency rates. Thus, you must ask yourself why not bid on the "D" rated individual. You only have a 1% (est.) credit default risk but a roughly an 8% greater interest rate.
(i) The key to identifying and bidding on any loan is looking for what I consider an inflection point. Has the person turned the corner from a credit disaster and is well on their way to financial bliss. Or, are they an "AA" rated individual with a $7600/month mortgage note in California and have depleted their savings?
(j) Consider the implications of the pictures or the absence thereof. Also consider whether or not their decision to autofund is based on desperation or some other reason. For further comments see my postings on the subject (posting one, posting two). Warning: Postings "one" and "two" are not necessarily ground truth. They’re merely observations with an element of conjecture thrown in.
Money Management:
(a) Don't make large lump sum deposits into your Prosper account. Doing so only precludes you from collecting interest on that money in your banking account. Instead it's best to making multiple transfers each week. Keep in mind that 3pm PST is the deadline for submitting transfer requests. Requests submitted after this time incurs an extra day of processing.
(b) To get an idea of the best time for bank transfers, you may want to read my post on the subject.
(c) For Small Budget Lenders: If you have a small budget, you can make deposits of as little as $25 (recently reduced from $50). Recommend making $25 deposits when your cash balance and payments in transit add up to $25. This will allow you to have a full $50 to bid in about four or five days.
Groups:
(a) Don't join a group unless you have a need to borrow money. You can get any of the group rewards as a lender.
Advanced Search Filters:
(a) Recommend you set up loan search filters in roughly the same manner I outline in paragraph "3" of the following tips post. I still follow the filter strategy mentioned in this post with one main exception. I now bid on loans with DTI's as high as 60% if:
1) they rent
2) their spouse or life mate contributes significantly to household expenses
3) they own or owe on a mortgage but have significant equity (50% or better) that can be tapped in an emergency.
Subscribe to:
Posts (Atom)